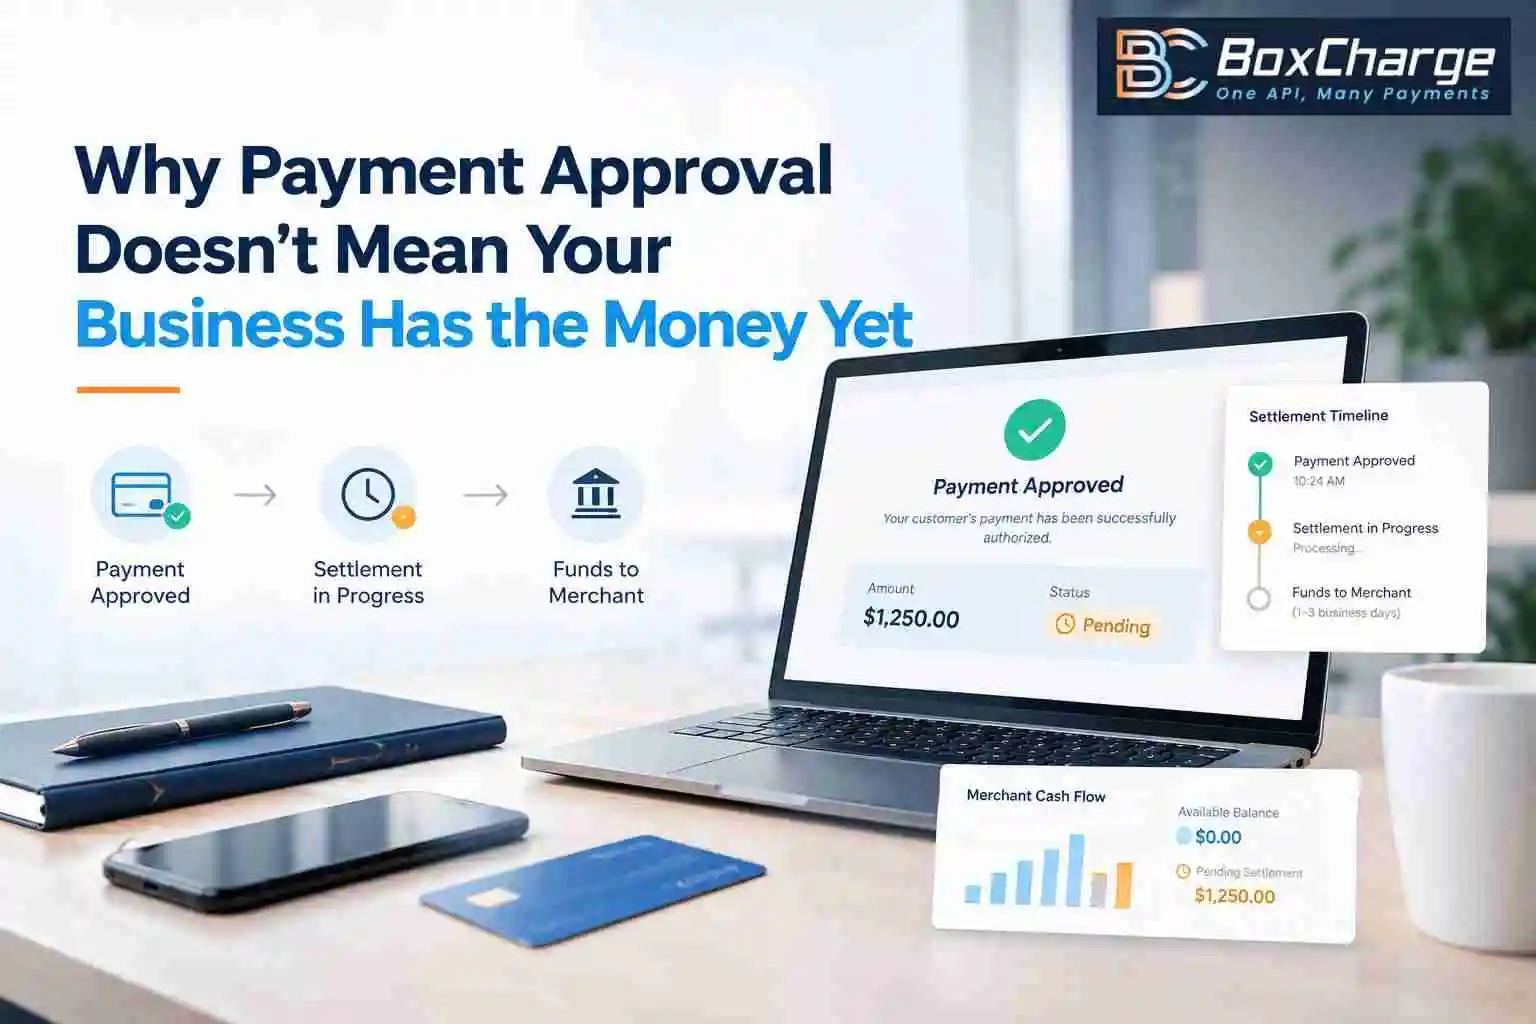
Getting a customer’s payment approved feels like the finish line, but payment approval doesn’t mean your business has the money yet. In reality, for many online businesses—especially high-risk merchants—it is only one step in a much longer payment journey.
A card transaction can receive an approval response from the issuer while the merchant is still waiting for the funds to move through authorization, capture, settlement, and payout. Depending on the payment setup, reserves, risk reviews, weekends, banking cutoffs, and the merchant’s agreement with its acquirer, the money may not reach the business bank account immediately.
This distinction matters because payment approval and merchant funding are not the same thing.
For a low-risk business processing predictable transactions, the delay may simply be a cash-flow inconvenience. For a high-risk merchant account, however, the consequences can be much larger. A delayed payout can affect advertising budgets, supplier payments, refunds, payroll, inventory, and day-to-day operating capital.
What Happens After a Customer’s Payment Is Approved?
When a customer enters card details and completes checkout, several different stages can occur before the merchant actually receives the money.
A simplified payment flow looks like this:
Customer payment → Authorization → Capture → Clearing → Settlement → Merchant payout
Each stage serves a different purpose.
1. Authorization
Authorization is the issuer’s response to the payment request.
The issuing bank checks factors such as available funds or credit, card status, transaction information, and applicable fraud controls. If the transaction passes those checks, the payment receives an approval response.
But an authorization is not the same as money arriving in the merchant’s bank account.
The approval essentially means the transaction has been authorized within the card network process. The merchant still has to complete the relevant downstream stages.
2. Capture
Capture is when the merchant formally requests the authorized transaction to be processed for settlement.
Some businesses use automatic capture, while others capture transactions later—for example, when an order ships.
This distinction can create confusion for merchants looking at their payment dashboard. A transaction may appear successful while the corresponding funds have not yet become available for payout.
3. Clearing and Settlement
After capture, transaction information moves through the payment ecosystem for clearing and settlement.
At this point, the transaction is moving toward the stage where funds are reconciled between the relevant financial institutions.
This is where terms such as settlement period, settlement time, and merchant funding become particularly important.
4. Merchant Payout
Finally, the payment processor or acquiring bank transfers available funds to the merchant’s designated bank account according to the agreed payout schedule.
That might be daily, on business days, or according to another schedule defined in the merchant agreement.
So when a dashboard says “payment approved,” it does not necessarily mean “cash is now available in your bank account.”
Why Is Approved Payment Still Not in My Bank Account?
The most common reason is simply that authorization happens before settlement and payout.
However, several additional factors can affect when funds become available.
Settlement schedules
Every merchant account operates according to a settlement arrangement.
For example, a business may have a T+1 or T+2 settlement structure, meaning funds are generally settled after one or two applicable business days rather than immediately after authorization.
The exact timing depends on the payment provider, acquiring bank, transaction type, location, currencies, and contractual terms.
Weekends and bank holidays
A payment approved late on Friday can follow a different timeline from one approved early on Monday.
Banking and settlement calendars can introduce additional delays, particularly for merchants processing internationally.
Cutoff times
Some acquirers and processors operate according to daily processing cutoffs. Transactions submitted after a cutoff may be included in a later settlement cycle.
For a merchant watching cash flow closely, even a one-day difference can matter.
Refunds, chargebacks, and adjustments
The amount eventually paid to the merchant may not simply equal the total of all approved transactions.
Refunds, chargebacks, processing fees, rolling reserves, chargeback fees, currency conversion costs, and other adjustments can affect the amount available for payout.
This is why approved transaction volume and available merchant balance can look very different.
Why This Becomes a Bigger Problem for High-Risk Merchants
For high-risk businesses, payment approval is only part of the challenge.
Industries such as online gaming, adult entertainment, digital services, nutraceuticals, travel, forex, subscriptions, and certain regulated or higher-chargeback business models can face additional underwriting and risk controls.
The issue isn't necessarily that every transaction will be delayed. Rather, high-risk merchant accounts can operate under more restrictive risk-management arrangements, depending on the acquiring relationship and business profile.
A merchant might see successful transactions accumulating in its payment dashboard while the expected payout is lower than anticipated.
That creates a difficult situation.
Imagine an online business generates £50,000 in approved card payments during a busy week. The owner may assume that the entire amount is immediately available to pay suppliers, purchase advertising, or cover operating costs.
But the actual amount available for payout could be affected by:
Processing fees
Rolling reserves
Settlement timing
Refunds
Chargebacks
Currency conversion
Risk reviews
Compliance-related holds
Previous negative balances
The result is a familiar high-risk merchant problem: revenue appears healthy on the payment dashboard, but working capital is still tight.
Rolling Reserves Can Make the Difference
One of the most important concepts for high-risk merchants to understand is the rolling reserve.
A rolling reserve is an amount withheld from transaction proceeds for a defined period as protection against potential future chargebacks, refunds, or other liabilities.
For example, under a hypothetical reserve arrangement, an acquiring partner could retain a percentage of processed volume and release it later according to the agreed reserve schedule.
This means a merchant processing £100,000 cannot automatically assume that £100,000 will arrive in its operating account.
The merchant needs to understand its:
Gross processing volume → Fees → Reserve → Adjustments → Net available payout
This is especially important when building a cash-flow forecast.
A business can be profitable on paper and still experience a working-capital squeeze if too much money remains tied up in the payment cycle.
High-Risk Account Holders Often Face a Cash-Flow Timing Problem
This is one of the less obvious pain points of operating a high-risk merchant account.
The merchant may have:
Customers actively purchasing
Strong payment approval rates
Increasing transaction volume
Healthy sales revenue
Yet the business may still struggle to access its funds when it needs them.
This becomes particularly painful during rapid growth.
Suppose a merchant increases advertising expenditure because sales are rising. Marketing costs must often be paid immediately, while card revenue may settle later.
At the same time, suppliers may require upfront payment.
Payroll has its own schedule.
Refund requests can arrive before the original transaction has fully settled.
A chargeback can create another liability.
Suddenly, a business that looks financially strong from a sales perspective can experience a payment cash-flow gap.
That is why experienced merchants don't manage their finances around approved transaction volume alone.
They manage around actual available funds and expected settlement dates.
Payment Approval vs Settlement vs Payout: What’s the Difference?
Payment approval, settlement, and payout happen at different points in the payment process. An approved transaction does not necessarily mean the merchant can immediately use the funds.
Stage | What happens | Does the merchant have the money? |
Payment Approval | The card issuer approves the customer's transaction request. | No |
Settlement | The transaction is processed between the payment ecosystem participants and the funds are settled to the acquiring side. | Not necessarily |
Merchant Payout | The payment provider or acquirer sends the merchant's available funds to its designated bank account according to the payout schedule. | Yes, once credited and available |
In simple terms
Approval = the customer's payment was authorized.
Settlement = the transaction's funds are being settled through the payment system.
Payout = the merchant receives its available funds in its bank account.
This is why a merchant can see a payment marked “approved” in its payment dashboard while the money is still unavailable for business use. Settlement schedules, reserves, refunds, chargebacks, processing fees, compliance reviews, and payout timing can all affect when the merchant actually receives the funds.
For high-risk merchants, understanding this difference is especially important because reserve requirements and additional risk controls can have a greater impact on the timing and amount of available funds.
Understanding these distinctions can prevent one of the most common merchant account cash-flow mistakes: treating approved sales as immediately accessible cash.
What Can Cause a Merchant Payout to Be Held?
A payout hold does not always mean something has gone wrong.
Payment providers and acquiring banks monitor transactions for financial and operational risk. A review may occur when transaction activity differs significantly from the merchant's approved profile.
Examples can include:
Sudden transaction growth
A business that historically processes £20,000 per month suddenly processing £200,000 can attract additional review.
This doesn't automatically indicate misconduct. It can simply represent a material change in processing behavior that requires reassessment.
Higher-than-expected chargebacks
Chargebacks increase the potential financial exposure for an acquirer. Persistent chargeback activity can therefore affect how a merchant relationship is managed.
Transactions outside the approved business model
If actual processing activity differs materially from what was described during underwriting, additional questions may arise.
For high-risk businesses, accurate underwriting information is therefore particularly important.
Compliance reviews
Know Your Customer (KYC), Anti-Money Laundering (AML), sanctions screening, transaction monitoring, and other compliance procedures can affect payment processing and funding timelines.
This is one reason merchants should avoid choosing a payment provider based purely on headline processing rates.
How High-Risk Merchants Can Reduce Payment-Related Cash-Flow Problems
The goal isn't simply to find a processor that says “approved.”
The more important question is:
Q: What happens to my money after the transaction is approved?
Before opening or changing a merchant account, ask detailed questions about the complete funding structure.
Understand the settlement schedule
Ask whether settlement is T+0, T+1, T+2, or another arrangement.
Also ask whether weekends and bank holidays affect settlement.
Ask about reserves upfront
Don't wait until your first large payout to discover that a reserve applies.
Ask:
Is a rolling reserve required?
What percentage is held?
How long are funds retained?
Under what conditions can the reserve change?
Check payout currencies
For international businesses, currency conversion can introduce additional costs and operational complexity.
A payment solution supporting appropriate settlement currencies can make international cash management easier.
Understand the provider's risk policy
A good high-risk payment processing setup should be built around the actual business model.
Merchants should understand what transaction volumes, countries, products, refund rates, and customer profiles their account is designed to support.
Build cash flow around net settlement
Don't forecast cash based on gross approved transactions.
Instead, calculate:
Expected sales − fees − reserves − refunds − other adjustments = expected available funds
This provides a much more realistic view of working capital.
What Should Merchants Look for in a Payment Provider?
For high-risk businesses, payment processing should be evaluated as a complete financial infrastructure rather than a simple checkout feature.
Look beyond:
Payment acceptance
Processing fees
Card coverage
Also examine:
Settlement speed
Payout schedules
Reserve requirements
Chargeback management
Fraud prevention
Multi-currency support
Acquirer relationships
Transaction monitoring
Reporting and reconciliation
Account stability
Support during compliance reviews
A high-risk merchant account provider should be able to explain these processes clearly before onboarding.
If a provider focuses heavily on getting your account approved but gives vague answers about settlement and reserves, that is something worth investigating before you start processing significant volume.
The Bottom Line: Approved Doesn't Mean Available
Payment approval is an important milestone, but it isn't the same as receiving usable business funds.
The complete payment journey includes authorization, capture, clearing, settlement, and payout. For high-risk merchants, additional factors such as rolling reserves, chargebacks, compliance reviews, transaction monitoring, and payout schedules can have a meaningful impact on cash flow.
That is why businesses looking for high-risk payment processing, international merchant accounts, or more reliable merchant payment solutions should evaluate the entire funding cycle—not just whether their customers can successfully pay.
At BoxCharge, the focus should be on understanding the merchant's business model, processing requirements, risk profile, and settlement needs before building a payment strategy. For businesses where cash flow and payment continuity directly affect growth, the right merchant account isn't simply the one that gets payments approved. It's the one whose approval, settlement, risk controls, and payout structure make commercial sense for the business.
Need a Merchant Account Built Around Your Cash Flow?
Getting a payment approved is only one part of the payment process. If settlement delays, rolling reserves, payout schedules, or unexpected payment holds are putting pressure on your working capital, it may be time to review your payment setup.
BoxCharge helps businesses explore payment processing solutions designed around their business model, risk profile, transaction volume, and settlement requirements.
Don’t plan your growth around approved transactions alone. Talk to BoxCharge about building a more reliable payment and settlement strategy for your business.